


Managing your finances and saving money can be daunting, especially if you are new to budgeting and money management. However, with the right strategies, you can learn how to manage your finances and save money properly.
Budget Plan

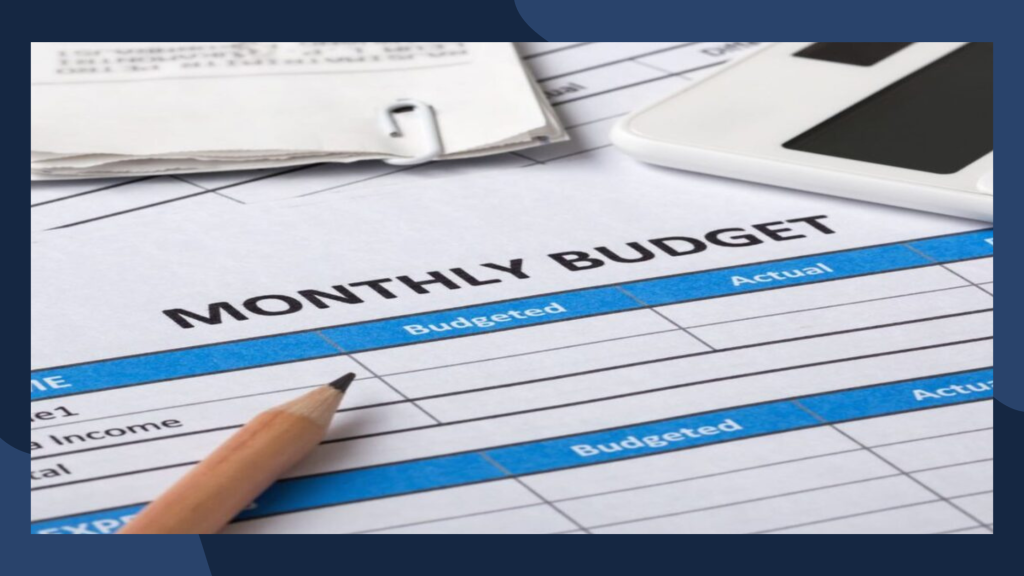
A budget is a plan that outlines how you will spend and save your money. It is vital to create a budget that is realistic and achievable. This section will provide steps to help you create a budget plan.
Step 1: Calculate Your Income
The first step in creating a budget is to calculate your total income. This includes all sources of income, such as wages, investments, and government benefits. It is essential to be as accurate as possible when calculating your income.
Step 2: Calculate Your Expenses
The next step is to calculate your total expenses. This includes all your fixed costs, such as rent, utilities, and car payments, as well as variable expenses, like groceries, entertainment expenses, and clothing. It is essential to be as accurate as possible when calculating your costs.
Step 3: Set Financial Goals
Once you have calculated your income and expenses, it is important to set financial goals. These goals should be realistic and achievable. Examples of financial goals include saving for retirement, paying off debt, or building an emergency fund.
Step 4: Create a Budget
Once you have calculated your income and expenses and set financial goals, it is time to create a budget. A budget should include all your income and expenses and be updated regularly. It is essential to be realistic and ensure it is achievable.
Step 5: Track Your Spending
The final step in creating a budget is to track your spending. This can be done by keeping receipts and tracking expenses in a spreadsheet or budgeting app. Tracking your spending will help you stay on track and ensure you are sticking to your budget.
Benefits Of Automating Your Savings
Automating your savings is a great way to ensure you consistently set aside money for the future. It can also help you reach your financial goals faster and more efficiently.
One of the main benefits of automating your savings is that it helps you to save consistently. By automatically transferring your checking account to your savings account, you can ensure that you are constantly setting aside money for the future. This can help you to reach your financial goals faster and more efficiently.
Another benefit of automating your savings is that it helps reduce the temptation to spend. When money is automatically transferred from your checking account to your savings account, you are less likely to be tempted to spend it on unnecessary items, which can help you save more money in the long run.
Cut Unnecessary Expenses
Cutting unnecessary expenses is an integral part of financial planning. It can help individuals and families save money and reduce debt. Here are some tips for cutting unnecessary costs:
- Start by making a budget that outlines all of your income and expenses. This will help you identify areas where you can cut back.
- Track your spending for a few weeks to understand where your money is going.
- Eating out can be expensive. Limit the number of times you eat out monthly and cook at home instead.
- Entertainment costs can add up quickly. Instead of spending money on expensive activities, find free or low-cost alternatives.
- Compare prices for items you must buy and look for coupons or discounts.
- Review your subscriptions and cancel any that you don’t use or need.
- Turn off lights and appliances when not in use and consider switching to energy-efficient models.
Benefits Of Investing Early
Investing early has many benefits that can help individuals reach their financial goals. It allows individuals to take advantage of compounding, which is the ability of an asset to generate earnings, which are then reinvested to generate revenues. This process can help individuals build wealth over time. Additionally, investing early can help individuals take advantage of the stock market’s long-term growth potential.
Compounding is one of the most potent benefits of investing early. When an individual invests early, they can take advantage of the compounding effect, which is the ability of an asset to generate earnings, which are then reinvested to generate revenues. This process can help individuals build wealth over time. For example, if an individual invests $1,000 at a 10% return after ten years, the investment would be worth $2,593. If the same individual invested $1,000 at a 10% rate of return for 20 years, the investment would be worth $6,727. This demonstrates the power of compounding and how it can help individuals build wealth over time.
Another benefit of investing early is that it allows individuals to take advantage of the stock market’s long-term growth potential. The stock market has historically provided higher returns than other investments over the long term. This is because stocks are more volatile than other investments, meaning they can experience more considerable gains and losses over short periods. Therefore, investing early can help individuals take advantage of the stock market’s long-term growth potential.
Tax Refund
Making the most of your tax refund can be a great way to improve your financial situation. By taking the time to plan and make intelligent decisions, you can use your refund to make a positive impact on your finances. Here are some tips to help you maximize your tax refund:
- If you have any outstanding debt, such as credit card or student loans, use your tax refund to pay it off. This will help you save money in the long run by reducing the amount of interest you pay.
- Consider using your tax refund to invest in yourself. This could include taking a class to learn a new skill, starting a business, or investing in a retirement account.
- Put some of your tax refunds into a savings account. This will help you build a financial cushion for unexpected expenses or when you must make a large purchase.
- Consider donating some of your tax refunds to a charity or cause you care about. This is a great way to impact the world and feel good about your contribution positively.
By taking the time to plan and make intelligent decisions, you can use your tax refund to make a positive impact on your finances. With careful planning and wise investments, you can make the most of your tax refund and improve your financial situation.
Avoid Impulse Buying
Impulse buying is a common problem that can lead to overspending and financial hardship. To avoid impulse buying, it is crucial to be aware of the triggers that lead to it and to develop strategies to resist the urge.
It is essential to recognize the triggers that lead to impulse buying. Common triggers include boredom, stress, and attractive displays or sales. Once these triggers are identified, developing strategies to resist the urge to buy is essential.
One strategy is to create a shopping list. This will help focus on the needed items and avoid unnecessary purchases. Additionally, it is essential to consider the purchase before making it. This can be done by waiting 24 hours before purchasing or asking oneself if the item is needed.
Another strategy is to avoid shopping when feeling emotional. Shopping when stressed, bored, or lonely can lead to impulse buying. Finding other activities to do when handling these emotions is essential, such as going for a walk or talking to a friend.
It is also essential to be aware of the financial consequences of impulse buying. Impulse buying can lead to overspending and economic hardship. It is crucial to consider the long-term financial implications of a purchase before making it.
It is possible to avoid impulse buying and its associated financial consequences by recognizing the triggers that lead to it and developing strategies to resist the urge.
Credit Card Rewards
Credit card rewards can be a great way to save money and get more out of your purchases. To make the most of your credit card rewards, it is crucial to understand how they work and how to maximize their value.
It is essential to understand the different types of rewards available. Most credit cards offer cash back, points, or miles. Cashback rewards are typically a percentage of the purchase amount credited to the cardholder’s account. Points and miles are typically earned for every dollar spent and can be redeemed for travel, merchandise, or gift cards.
Understand the terms and conditions associated with the rewards program. Many rewards programs have expiration dates, minimum redemption amounts, and other restrictions. It is essential to read the fine print to ensure you take full advantage of the rewards program.
Choose a rewards program that best fits your spending habits. If you travel frequently, a rewards program that offers miles may be the best option. If you prefer to shop online, a rewards program that provides cashback may be the best option.
Use your credit card responsibly. Paying off your balance in full each month will help you avoid interest charges and maximize the value of your rewards.
It is also beneficial to stay current on the latest offers and promotions. Many credit card companies offer bonus rewards for specific purchases or meeting certain spending thresholds.
By understanding how credit card rewards work and taking advantage of the latest offers and promotions, you can maximize your rewards and get more out of your purchases.
Shop Smartly For Insurance
Shopping for insurance can be daunting, but it doesn’t have to be. By following a few simple steps, you can get the best coverage for your needs at the best price.
It’s beneficial to understand the different types of insurance available. Other policies cover other risks, so knowing what you need and don’t is essential. Once you’ve identified the type of insurance you need, you can start researching different companies and policies.
When researching policies, it’s essential to compare the coverage and cost of each approach. Make sure to read the fine print and understand the terms and conditions of each policy. It’s also important to consider the company’s reputation and the customer service they provide.
Once you’ve narrowed your choices, it’s time to get quotes. You can get quotes from multiple companies to compare prices and coverage. Make sure to ask about any discounts or special offers that may be available.
Additionally, it’s a must to review your policy regularly. Ensure that your coverage is still adequate for your needs and that you’re not paying too much for your policy.
By following these steps, you can get the best coverage for your needs at the best price. Shopping for insurance doesn’t have to be a daunting task. With some research and comparison, you can find the right policy.
Make The Most Of Your Retirement Savings
Retirement savings are an essential part of financial planning for the future. Making the most of your retirement savings is necessary to ensure a comfortable retirement. Here are some tips to help you make the most of your retirement savings:
Start Early
The earlier you start saving for retirement, the more time your money has to grow. Compound interest can help your money grow faster, so the sooner you start saving, the better.
Make Regular Money Contributions
Regular contributions to your retirement savings account can help you reach your goals faster. Consider setting up automatic contributions from your paycheck or bank account to ensure you consistently save.
Take Advantage Of Tax Benefits
Many retirement savings accounts offer tax benefits, such as tax-deferred growth or tax-free withdrawals. Make sure you understand the tax implications of your retirement savings account and take advantage of any available tax benefits.
Diversify Your Investments
Diversifying your investments can help reduce risk and maximize returns. Consider investing in various stocks, bonds, and other assets to help spread your risk.
Monitor Your Investments
Monitoring your investments to ensure they are performing as expected is essential. Consider working with a financial advisor to help you make informed investment decisions.
By following the tips above, you can maximize your retirement savings and ensure a comfortable retirement.
Employer Benefits
Employer benefits are essential to any job, and making the most of them is crucial. Here are some tips for getting the most out of your employer benefits:
- Take the time to read through your benefits package and understand what is included. Ask your employer or human resources department for clarification if you have any questions.
- Many employers offer retirement benefits such as 401(k) or pension plans. Take advantage of these benefits and contribute as much as you can.
- Make sure you are taking advantage of your health insurance benefits. This includes preventive care, annual physicals, screenings, and other covered services.
- Many employers offer other benefits such as tuition reimbursement, flexible spending accounts, and discounts on products and services. Make sure you are taking advantage of these benefits.
- If your employer does not offer enough benefits, you can always negotiate for better ones. Talk to your employer or human resources department to see if they can provide more.
Side Hustle Income
Side hustles are becoming increasingly popular to supplement income and gain financial freedom. While side hustles can be a great way to make extra money, making the most of your side hustle income is essential.
- Setting goals is vital to making the most of your side hustle income. Think about what you want to achieve with it and set realistic goals that you can work towards.
- Tracking your income is essential for maximizing your side hustle income. Keeping track of your payments will help you identify areas where you can increase your earnings and identify any potential problems.
- Investing your side hustle income is a great way to maximize your earnings. Investing your money in stocks, bonds, mutual funds, or other investments can help you grow your wealth over time.
- Saving for retirement is vital to maximizing your side hustle income. Setting aside a portion of your income for retirement will help you build a secure financial future.
- Paying off debt is another excellent way to maximize your side hustle income. Paying off debt can help you reduce monthly expenses and save money for other financial goals.


